Economy
Mustafa Chike-Obi: Large Foreign Reserves Do Not Necessarily Mean Nigerians Are Better Off
ECONOMY | FOREIGN EXCHANGE | NIGERIA | OCTOBER 18, 2026
Nigeria’s rising foreign exchange reserves may strengthen the country’s ability to meet international payment obligations, but they do not automatically mean households are better off or that the economy’s underlying problems have been resolved.
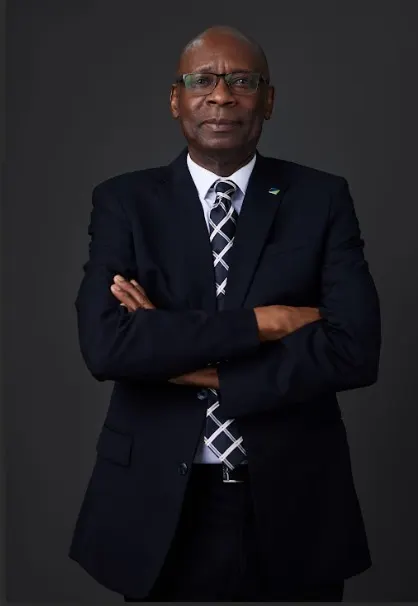
That is the central argument made by Mustafa Chike-Obi, former chairman of Fidelity Bank, in an interview on the Policy Without Politics podcast, which he co-hosts with Ken Ikpe.
In remarks reported by TheCable on October 18, Chike-Obi questioned the economic cost of maintaining Nigeria’s reserves and argued that policymakers should determine how much the country needs based on its foreign payment obligations, rather than assuming that a larger headline figure is always better.
The debate comes as official data cited in the report put Nigeria’s gross foreign reserves at $55.09 billion on October 14, 2026, up from $51.94 billion on July 28. The increase is an important indicator of the country's external financial position, but interpreting it requires more than looking at the headline total.
What Chike-Obi says Nigeria is paying to hold reserves
Chike-Obi estimated that maintaining reserves of $52 billion to $53 billion costs Nigeria more than $10 billion annually.
His calculation rests on three figures:
Estimated return on liquid reserve assets
3%
Estimated naira funding cost
20%
His estimated annual cost differential
17 percentage points
Applied to $52–53 billion, this produces an estimated annual cost exceeding $10 billion in his calculation.
He argued that foreign reserves are generally held in liquid financial instruments abroad, including deposits and other qualifying assets, so that the country can access foreign currency when required.
In his view, the government should calculate the reserve level needed to meet upcoming foreign obligations and maintain an appropriate buffer, rather than pursue the highest possible total.
An important qualification to the $10 billion estimate
Chike-Obi’s figure is his estimate, not an independently established annual bill published by the Central Bank of Nigeria (CBN).
The calculation compares an estimated return on dollar-denominated reserve assets with a stated cost of naira funding. To establish the actual net cost, analysts would need to examine how the reserves were accumulated and financed, the relevant liabilities and their interest rates, changes in the naira-dollar exchange rate, and the composition and returns of the reserve portfolio.
Applying the 17-percentage-point difference to the entire reserve stock is not, by itself, sufficient to prove that Nigeria incurs a cash loss of more than $10 billion every year. The distinction matters because an estimated opportunity cost is not necessarily the same as an actual fiscal expenditure.
Why Nigeria needs foreign reserves
The CBN identifies three broad objectives of reserve management: preserving capital, maintaining liquidity and earning an appropriate return within acceptable risk limits. Reserves are intended to help the monetary authorities finance external payment imbalances, intervene in foreign exchange markets when necessary and meet other official obligations.
In practical terms, reserves can help Nigeria:
- Pay for imports and external obligations: Foreign currency is needed for international payments, including payments by government and other authorised entities.
- Support foreign exchange market stability: The CBN can use reserves for interventions when it considers them necessary.
- Build confidence among lenders and trading partners: A credible reserve position can reassure external creditors and suppliers that Nigeria has foreign currency available to meet obligations.
- Absorb external shocks: Reserves can provide a buffer when oil receipts, capital inflows or other sources of foreign currency weaken.
However, reserves do not directly measure the income of ordinary Nigerians, the strength of domestic production, the availability of jobs or the affordability of food, transport and housing.
That is the key distinction behind Chike-Obi’s argument: a stronger external balance sheet is not the same thing as an improvement in every part of the domestic economy.
What the latest reserve figures tell us
Gross foreign reserves, selected reported dates in 2026
Nigeria's gross foreign reserves
Reported reserve levels in US dollars, in billions.
0bn15bn30bn45bn60bnJul 28Oct 9Oct 14
The reported rise in reserves is a real development worth monitoring. But the figures should be interpreted carefully:
- Gross reserves are not the same as net reserves. Gross reserves measure qualifying external assets; net reserves take account of relevant foreign-currency liabilities or other deductions under the applicable methodology.
- The total does not reveal the full cost of maintaining the reserves. That requires information about the portfolio, funding and liabilities.
- A rising reserve balance does not automatically translate into lower prices. Food prices, transport costs and other living expenses depend on multiple domestic and international factors, including exchange-rate movements, production and distribution costs.
Separate reporting citing CBN Governor Olayemi Cardoso put net reserves at about $46 billion, illustrating why gross and net figures should not be treated as interchangeable.
The wider economic question: who benefits?
For households, the most immediate question is whether changes in Nigeria’s external position lead to more stable economic conditions.
A stronger reserve buffer may help reduce vulnerability to foreign exchange shortages and external shocks. But its benefits depend on how it is managed and whether broader economic policies support domestic production, investment, employment and purchasing power.
There are therefore two separate questions for policymakers:
- How much foreign currency does Nigeria need to meet its external obligations and withstand shocks?
- How can the country manage those reserves efficiently while improving living standards and productive capacity at home?
Chike-Obi is challenging policymakers on the first question and arguing that reserve management should be assessed against its costs. The second question remains broader: even a well-managed reserve portfolio cannot, by itself, resolve the structural issues affecting household welfare.
Note:
Mustafa Chike-Obi’s warning is that Nigeria should not treat a large foreign-reserve figure as proof that the country is automatically better off. Reserves serve an important purpose, but the appropriate level, the cost of maintaining them and their contribution to economic stability all deserve scrutiny.
His estimate of an annual cost exceeding $10 billion should be understood as an argument based on his stated assumptions, rather than a verified government expenditure figure. The more useful test is whether reserve management protects Nigeria against external shocks at a reasonable cost—and whether the country’s wider economic performance ultimately improves the lives of its citizens.
Sources
TheCable — Mustafa Chike-Obi: Large foreign reserves don’t mean Nigeria is better off